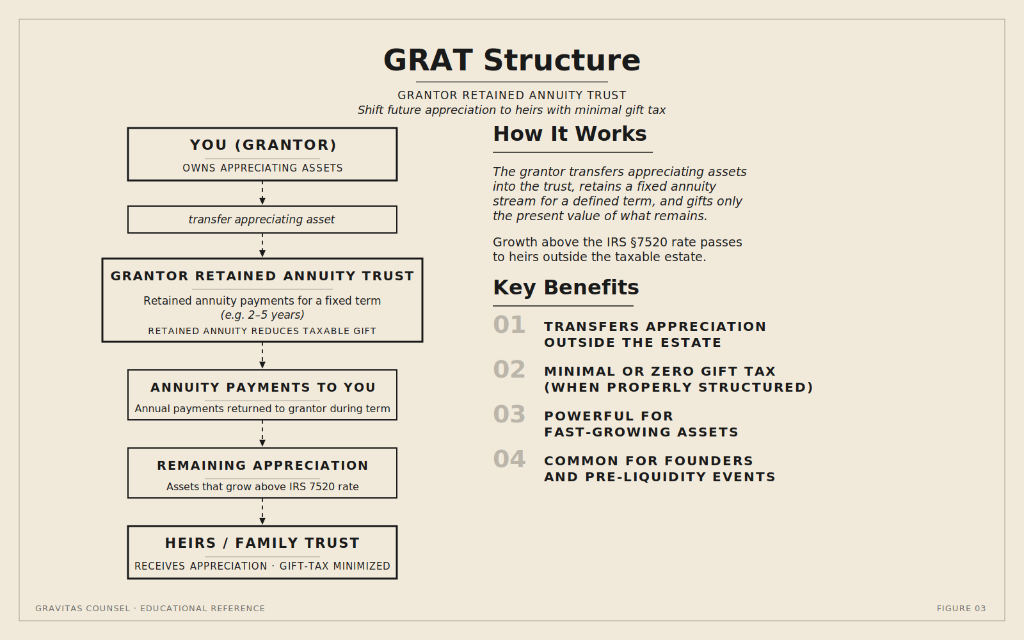
GRAT Structure
Shift future appreciation to heirs with minimal gift tax. A precision instrument for founders sitting on fast-growing assets, built to outrun the IRS hurdle rate.
Grantor Retained Annuity Trust
A GRAT is an irrevocable trust that holds an appreciating asset for a fixed number of years. The grantor receives annuity payments during the term. At the end, whatever remains inside the trust passes to heirs. If the asset grows faster than the IRS Section 7520 rate, the excess passes gift-tax-free.
The GRAT is the cleanest instrument in estate planning for shifting pre-liquidity appreciation out of the estate. Founders use it before an IPO or acquisition. Investors use it on concentrated positions. The downside risk is minimal: if the asset does not appreciate, the GRAT simply fails and the assets return to the grantor. The upside, when it works, is transformational.
The structures described here are architectural patterns that require careful customization to the specific facts of each client, jurisdiction, and set of planning objectives. These diagrams and summaries exist to build vocabulary and pattern recognition, not to substitute for qualified counsel.